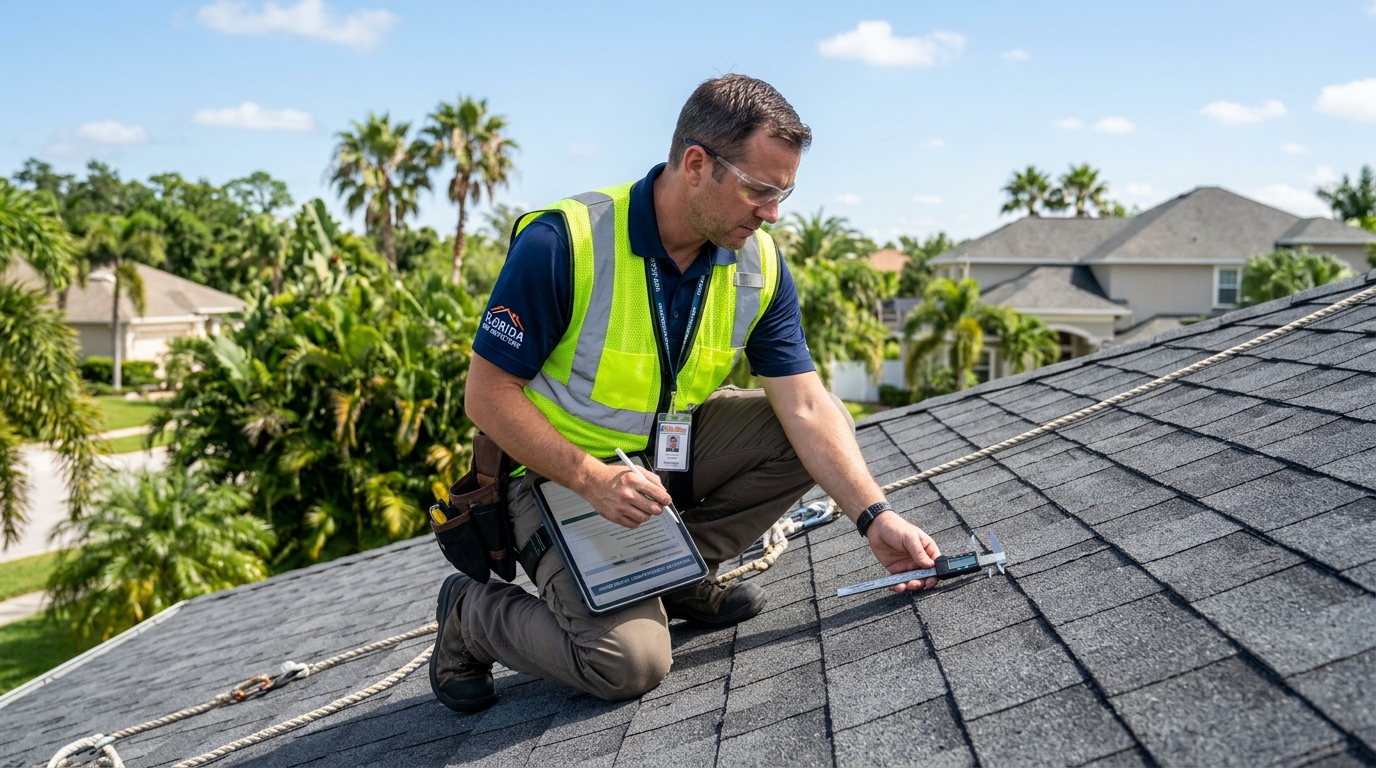
If your Florida homeowners insurance company has questioned the age of your roof, you may be wondering whether you really need to replace it, even if it isn't leaking.
For Tampa homeowners, this can be an expensive decision. You might receive a request for a roof inspection, be told to complete repairs, or get a non-renewal notice with a tight deadline. The first step is to find out whether the concern is your roof's age, its physical condition, or another insurance underwriting requirement.
Florida does not have a blanket law requiring every roof to be replaced at 15 years old. Under Florida Statute § 627.7011(5), certain homeowners' insurance decisions cannot be based solely on roof age. For qualifying roofs that are at least 15 years old, the law provides an inspection option before an insurer requires replacement as a condition of issuing or renewing a policy. If an authorized inspector finds at least five years of useful life remaining, the insurer cannot refuse to issue or renew the policy solely because of the roof's age. Read the Florida statute.
That protection matters, but it does not mean every older roof will qualify for coverage or that an insurer must accept any inspection report you provide. This guide explains what the law means, what to do if your insurer contacts you, and how to decide whether your roof needs a repair, further evaluation, or a full replacement.
1. Roof Age and Roof Condition Are Two Different Things
An older roof is not automatically a failing roof. Equally, a roof that looks fine from the driveway may still have underlying damage that needs attention.
Insurance companies evaluate both the roof's documented age and its physical condition when assessing risk. Understanding which issue your insurer has flagged helps you choose the right next step:
-
1
Roof Age: Generally determined by when the entire roof surface was permitted and installed in accordance with the applicable building code. Under Florida Statute § 627.7011(5)(d), a minor patch or replacing a few wind-blown shingles does not automatically reset the roof's legal installation age.
-
2
Roof Condition: Focuses on the current physical health of the roofing system today. Evaluators check for missing tabs, granule loss, cracked mortar or tiles, rusted flashings, and signs of attic moisture intrusion.
For example, a 17-year-old architectural shingle roof with sound, unlifted shingles may warrant a certified inspection to verify remaining life before you commit to replacement. Conversely, an 8-year-old roof with widespread storm hail strikes or improperly flashed valleys may require immediate repairs.
If you have noticed an active leak, missing shingles, or minor valley wear, start by exploring targeted roof repair services before assuming a full replacement is mandatory.
2. What Florida's 15-Year Roof Insurance Rule Actually Says
Florida Statute § 627.7011(5) establishes clear statutory rules governing how private property insurers evaluate roof age during policy issuance or renewal:
-
1
If your roof is less than 15 years old: An insurer may not refuse to issue or renew a qualifying homeowners insurance policy solely because the roof is less than 15 years old (§ 627.7011(5)(b)). However, an insurer may still decline coverage for separate lawful underwriting reasons, such as active leaks or unrepaired physical damage.
-
2
If your roof is 15 years old or older: Before requiring a full roof replacement as a mandatory condition for policy issuance or renewal, the insurer must allow the homeowner to have the roof inspected by an authorized inspector at the homeowner's expense.
-
3
If the inspection certifies at least 5 years of useful life remaining: The insurer cannot refuse to issue or renew the policy solely based on roof age if the authorized inspection report confirms the roof has 5 or more years of serviceable life remaining (§ 627.7011(5)(a)).
This statute protects homeowners against decisions made solely on age. It does not prevent an insurer from increasing deductibles, adjusting premiums, or acting on legitimate physical defects. Review the official statutory text on the Florida Senate portal and consumer guidance from the Florida Department of Financial Services (DFS).
3. Roof Inspection, Roof Certification, and a 4-Point Inspection
If your insurance carrier requests documentation, confirm the exact report required in writing before scheduling an inspection. These three terms are often confused:
-
1
Dedicated Roof Inspection: Conducted by a licensed roofing contractor or certified inspector focusing entirely on the roof covering, flashing integrity, ventilation, moisture intrusion, and estimated remaining useful life.
-
2
Roof Certification / Roof Condition Form: A standardized document (often the Citizens Roof Condition Certification Form) where an authorized professional formally certifies that the roof is free of active leaks and possesses at least 3 to 5 years of remaining useful life.
-
3
4-Point Inspection: A broad underwriting inspection requested on older Florida homes covering four primary systems: (1) Roofing, (2) Electrical, (3) Plumbing, and (4) Heating & AC. Review the Florida DFS homeowners overview for 4-point underwriting standards.
4. What to Do If Your Insurance Company Sends a Roof Notice
Receiving a 30-day notice or non-renewal threat can feel overwhelming. Follow these five practical steps before signing an expensive contract:
Read the Notice and Identify the Deadline
Determine whether the carrier is requesting an inspection report, specific repairs, or proof of replacement. Note the policy renewal date and response deadline immediately.
Ask Why the Roof Was Flagged
Contact your agent and ask for the exact underwriting reason. Did an aerial drone flyover spot loose shingles, or is the notice generated automatically by an estimated installation date?
Verify the Actual Roof Installation Date
Search municipal permit records on the Hillsborough County or City of Tampa building portal. Insurers often use county property appraiser estimates that may predate your roof's true permitted replacement date.
Confirm Accepted Inspector Credentials
If utilizing the Florida 15-year statutory inspection option, ask your agent which specific inspector qualifications (e.g. Florida State Certified Roofing Contractor CCC license) and forms your carrier requires.
Decide Between Repairs and Replacement
If the report confirms minor localized defects, obtain a written repair scope. If the inspection reveals brittle, granular-depleted shingles with less than 5 years of life, review replacement bids on our roof replacement service page.
5. Questions to Ask Your Insurance Agent Before Paying for a New Roof
Before spending thousands of dollars on a premature roof replacement, ask your insurance agent these five specific questions:
What is the exact reason for the roof-related notice?
Clarify whether the flag is strictly chronological age, an aerial photo observation, or a finding from a prior field adjuster.
What specific inspection report format will your underwriters accept?
Verify whether the carrier requires the Citizens Roof Condition Certification Form, a Florida licensed contractor letter, or a full 4-point inspection.
If the roof is 15+ years old, how will underwriters evaluate a 5-year useful life finding?
Confirm that the carrier complies with Florida Statute § 627.7011(5) and will maintain coverage if the inspector certifies at least 5 years remaining.
If repairs are completed, what documentation is required to clear the flag?
Ask if paid contractor invoices, municipal permit finals, and post-repair date-stamped photos will fully resolve the underwriting requirement.
Will my policy remain active while I complete the required inspection or repairs?
Request written confirmation of any deadline extension while licensed contractors perform assessments or permitted work.
6. A Simple Decision Guide for an Older Roof
Use this practical roadmap to determine your recommended course of action based on your specific situation:
-
1
Roof is under 15 years old & notice cites age alone: Request that your agent review the notice against Florida Statute § 627.7011(5)(b). Submit municipal permit documentation showing the roof's true permitted completion date.
-
2
Roof is 15+ years old: Request the statutory inspection option. Hire an authorized Florida State Certified contractor to inspect the roof for at least 5 years of remaining useful life.
-
3
Notice identifies specific localized defects: Request the insurer's photographic evidence in writing and schedule targeted roof repair work to satisfy the defect report.
-
4
Inspection certifies 5+ years of useful life: Submit the completed certification to the underwriting department and request written confirmation that the age flag is removed.
-
5
Inspection identifies widespread granular loss or brittle shingles: Compare full replacement quotes. Review our guide on How to Compare Roofing Estimates Line by Line and learn about roof change orders.
-
6
Carrier has issued a formal non-renewal notice: Contact your agent immediately to confirm the hard cutoff date. If the insurer refuses statutory inspection findings, explore alternative Florida carriers or contact the Florida DFS Consumer Assistance Division.
7. When Does Roof Repair Make Sense, and When Should You Consider Replacement?
The right solution depends on what is physically wrong with the roof and whether your insurer will accept completed repairs:
-
1
Targeted Roof Repair: Ideal when damage is isolated (e.g. cracked pipe boots, lifted valley shingles, or minor wind damage) while the broader roof field remains pliable and securely adhered. Explore Roof Repair Services →
-
2
Architectural Shingle Replacement: Recommended when shingles are shedding granules, curling at edges, or failing a brittle-shingle test. Modern architectural shingles provide 130 mph wind defense and qualify for insurance wind mitigation credits. Explore Shingle Roofing →
-
3
Tile Roof Evaluation & Restoration: Concrete and clay tiles can last 40+ years, but the underlying organic underlayment often fails after 20 years. An inspector will check tile fastener integrity and underlayment elasticity. Explore Tile Roofing →
-
4
Storm Damage Restoration: If recent hurricane gusts or thunderstorm microbursts damaged your roof, immediate temporary dry-in prevents structural rot while filing an insurance claim. Explore Storm Damage Repair →
-
5
Complete Re-Roofing: If useful life is under 5 years, a complete replacement stripped to bare plywood gives you guaranteed municipal sign-off and an updated Wind Mitigation Form (OIR-B1-1802). Explore Roof Replacement →
8. What This Means for Tampa Homeowners
In Tampa, Brandon, Riverview, and across Hillsborough County, local weather extremes, intense summer heat baking attics to 160°F and tropical storm wind shear, accelerate roof wear.
However, receiving an insurance notice does not mean you must immediately pay for a new roof. Take advantage of Florida Statute § 627.7011(5). Have an authorized, state-certified roofing contractor inspect the roof, verify the permit history, and document its true physical condition.
At Roof Works, our in-house mechanics have served Hillsborough County property owners since 1990. We provide honest, unbiased roof evaluations, photo-documented roof certifications, and code-compliant repairs and replacements.
Frequently Asked Questions
Does Florida law require a roof replacement at 15 years old?
No. Florida law does not establish a blanket requirement to replace every roof at 15 years. Under § 627.7011(5), an insurer cannot refuse to issue or renew a qualifying policy solely because a roof is under 15 years. For roofs 15+ years old, homeowners have the legal right to a statutory inspection before replacement can be mandated.
Can I get homeowners insurance in Florida with a 20-year-old roof?
Yes, provided the roof passes an authorized inspection certifying at least 5 years of remaining useful life and has no active leaks or severe physical defects. While the statute prevents non-renewal based solely on age, coverage and premium terms remain subject to insurer underwriting.
Will a small roof repair reset the roof's age?
No. Under Florida Statute § 627.7011(5)(d), localized repairs or partial shingle patches do not reset the legal age of the roof. Roof age is determined by the date the entire roof covering was permitted and installed.
Is a 4-point inspection the same as a roof certification?
No. A 4-point inspection covers four major home components (roof, electrical, plumbing, HVAC). A dedicated roof certification focuses exclusively on the roof's condition, materials, and useful life expectation. Confirm with your carrier which form they require.
What if my insurer rejects my inspection report?
Ask for the rejection reason in writing. Verify whether the inspector met statutory credentials or if a carrier-specific form was required. You can seek consumer mediation through the Florida Department of Financial Services or consult an independent insurance broker.
Should I replace my roof before contacting my insurance company?
Not automatically. First understand the carrier's specific objection, pull municipal permit history, and complete a formal roof evaluation. If the roof has substantial remaining life, you may save thousands of dollars by completing an authorized inspection.
Need Help Understanding Your Roof's Condition?
An insurance notice can make a roof replacement feel urgent, but the first step is establishing what your roof actually needs and what documentation your insurer will accept.
Roof Works is a family-owned roofing business with more than 34 years of experience in the Tampa roofing industry. We understand the complex interplay between Florida Building Code standards, statutory roof age rules, and insurance underwriting requirements.
If you have received an insurance notice, non-renewal letter, or inspection requirement, bring your paperwork to our team. We'll conduct an honest on-site inspection, identify whether code-compliant repairs can satisfy underwriting, or provide an upfront fixed replacement estimate.
Request a Roof Assessment → Or call direct: (813) 845-8300